

Read More

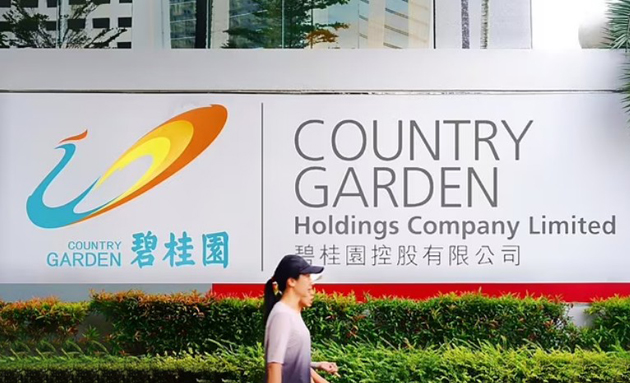
Once upon a time, Country Garden was extremely popular among Hong Kong retail investors. It was considered a mammoth too large to be allowed to fail.
Yesterday, the country's largest real estate developer closed at HK$0.8 a share. A year ago today, it was HK$2.32.
During its prime time in January 2018, Country Garden was worth over HK$17 a share.
History seems never tired of repeating itself.
Will Country Garden survive the current crisis to be robust again? We may not know the answer, but we do know it is always crucial to let retail investors understand the risk.
Country Garden was rated a model developer in the mainland recently at a time when its industry peer Evergrande Group was deep in trouble.
So it is ironic that the developer - which state media once boasted was financially healthy - has quickly degenerated into what is probably the biggest ticking bomb threatening the country's economic recovery.
As an old saying goes: "Three feet of ice does not form in a day's cold."
Mainland developers began displaying various degrees of stress after Beijing introduced a series of policies to crack down on a bubbling property sector.
Risks stemming from policy changes are real and the Hong Kong stock exchange should maintain the long-standing practice requiring companies - either listed or planning to list - to disclose risks in order to be fair to retail investors who lack the means to undertake indepth research on their own.
If the debt crisis facing Evergrande has been a major headache for Beijing policymakers, the current crisis facing Country Garden is quickly proving to be an even greater challenge for the decision makers.
It would have been much easier to deal with had the problem been only about Country Garden - if that were the case, it would have been a matter of just letting it fail.
But the problem goes beyond Country Garden itself, affecting dozens of industries upstream and downstream of the developer.
If it were it to collapse, tens of millions of jobs would be endangered and financial institutions that have continued to lend to this "financially healthy" developer would come under pressure.
That is why the market panicked as soon as Country Garden surprised investors with a profit warning and then an announcement suspending a quantity of onshare bonds.
The outstanding question is whether or not the central government will save it.
If it does not, could the knock-on effect throw the rest of the country's economy into uncertainty at a time when other economic drivers, including exports and domestic consumption, have already slowed to dangerous levels?
If so, would it set back long-standing efforts to put the real estate sector back on the "right track"? If Beijing has not splashed cash to rescue Evergrande, why would it contradict itself in the case of Country Garden?
When the group's chairman Yang Huiyan donated 20 percent of Country Garden Services Holdings, a property management unit of the group, to Guoqiang Public Welfare Foundation, a Hong Kong-incorporated charity under the name of Country Garden founder and Yang's father, the act raised many an eyebrow in Beijing.
It seems that Beijing has not yet arrived at a decision on the matter.