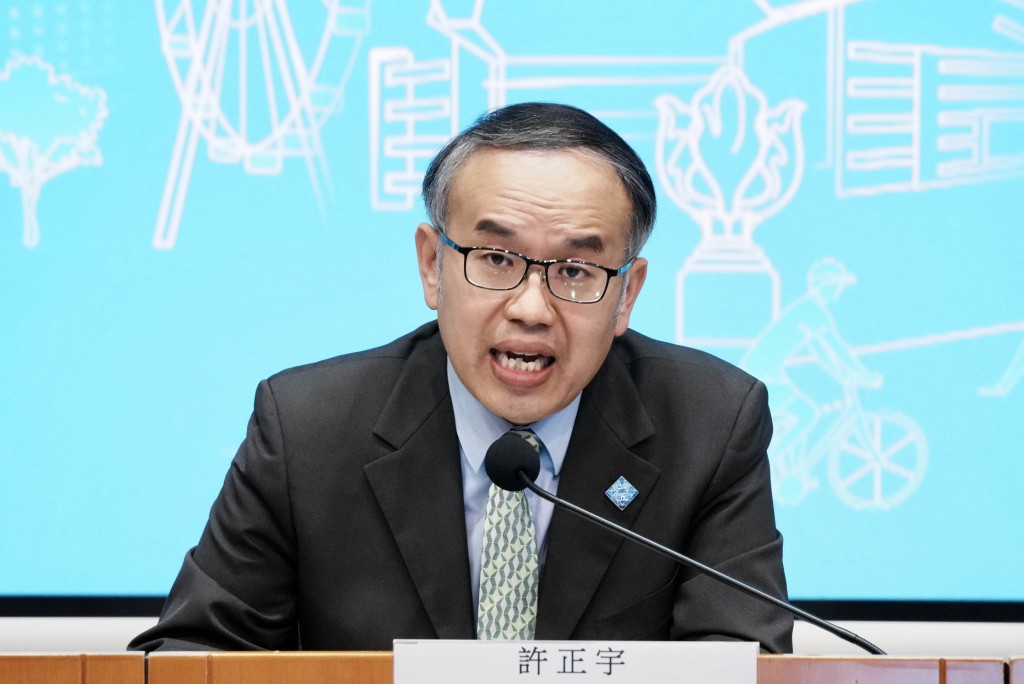
Hong Kong plans offer a preferential tax rate of as low as 5 percent for eligible companies that make contributions to the city for up to five years, Secretary for Financial Services and the Treasury Christopher Hui Ching-yu said at the Legislative Council’s financial affairs panel on Monday.
Enterprises can also earn an 8.25 percent tax rate – half the standard 16.5 percent corporate rate. The government first set out the preferential policy in the 2025 Policy Address to draw high-value industries and high-potential enterprises to Hong Kong, with the preferential tax regime added in the 2026 Policy Address. The amendment bill will be tabled at the Legislative Council in December, with the government targeting implementation in the 2027/28 year of assessment.
The regime aims to attract key industries, including advanced manufacturing, innovation and technology R&D, headquarters activities, logistics and supply chain management, and finance, Hui said.
Beyond meeting conditions such as carrying out qualifying activities, operating costs, and full-time employee numbers, applicants must also satisfy conditions on their investment plans and substantive contribution to Hong Kong's economy.
He noted that the preferential tax regime is one of several items in the preferential policy, alongside land disposal, subsidies, and tax concessions.
The regime is highly selective, Hui said, with the government screening enterprises that meet the relevant criteria and have development potential through a strict approval process. Both newly established enterprises and those already operating in Hong Kong may submit business plans through Invest Hong Kong and the Office for Attracting Strategic Enterprises to apply for tax concessions under the regime.
The Steering Committee on Preferential Policies for Attracting Industries and Investment, chaired by the Financial Secretary, will approve applications and set requirements on total expenditure and full-time employee numbers for approved enterprises, and may impose additional conditions on a case-by-case basis, Hui said.
He added that the proposed regime is designed to complement existing industry-specific preferential tax regimes, and that all income earned by eligible enterprises will continue to enjoy concessionary tax rates or profits tax exemptions without prior application.