

Read More

Night Recap - October 2, 2026
13 hours ago
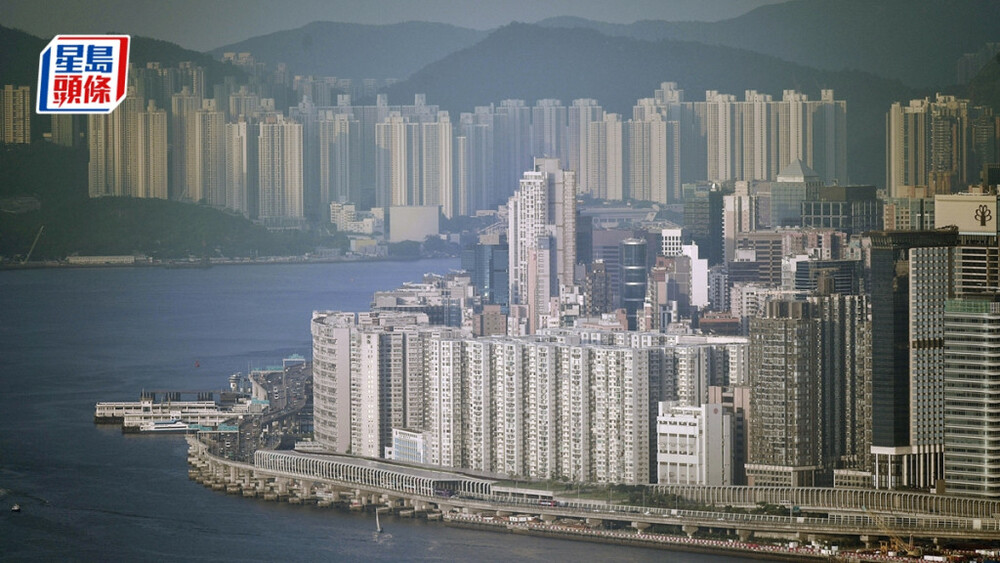
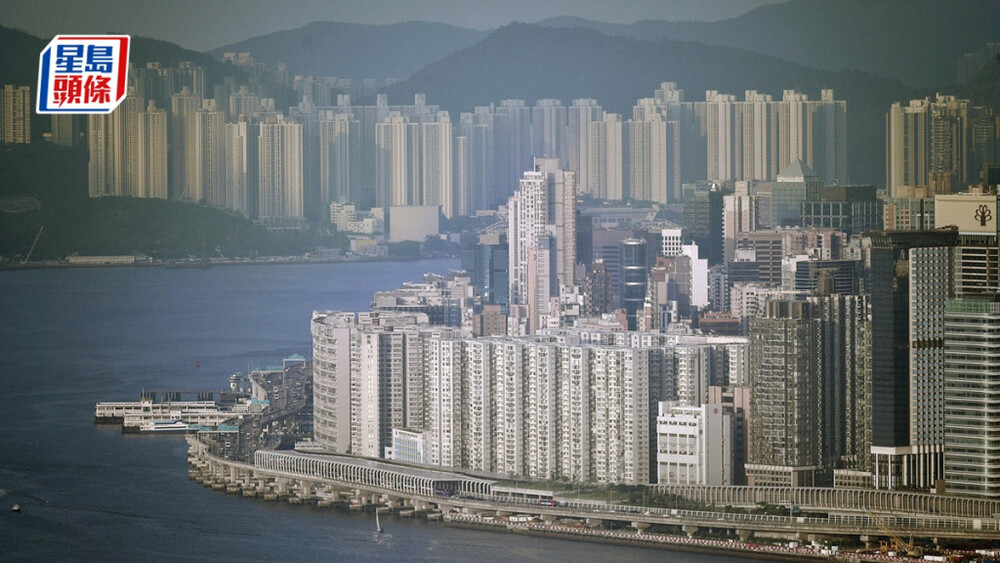
Hong Kong’s relaxation of residential mortgage rules is likely to do little to spur demand from homebuyers who remain deterred by surging interest rates, according to analysts.
In the first major easing since 2009, the government on Friday increased the loan-to-value ratio for some homes, allowing buyers to snap up properties with a smaller down payment.
The real estate industry has been under pressure from rising rates and a weak economy, with home prices falling 13% from their peak in 2021, according to the central bank.
Hong Kong’s base rate has climbed in line with the US Federal Reserve’s hikes since 2022 as the local currency is pegged to the greenback.
The Hong Kong Monetary Authority has consistently cautioned homebuyers of higher borrowing costs, with the Fed likely to continue raising rates this year, including once later this month.
The mortgage easing “is unlikely to help the city’s housing market right away. The reason — borrowing costs are elevated,” Eric Zhu, an economist at Bloomberg Economics, wrote in a note. “This is probably a bigger factor holding back buyers. And interest rates won’t come down until the Federal Reserve starts to ease monetary policy.”
Citigroup Inc. analyst Ken Yeung said the relaxation is likely to have a “negligible impact on Hong Kong residential sentiment.”
Transactions above HK$12 million only account for 12% of total volume, and already-high loan-to-value ratios for cheaper homes have had little effect, Yeung said.
He kept his view that home prices will fall 6% in the second half.
Sam Wong, an equity analyst at Jefferies LLC, said the new rules won’t alter his forecast for home prices to remain stable this year, citing limited purchasing power from further potential prime rate hikes. Still, he added that large banks could see “strong mortgage growth.”
Others were more bullish on the impact of the easing. Goldman Sachs Group Inc. analysts including Gurpreet Singh Sahi said the move could help raise transaction volumes and physical prices, as well as benefit banks.
They raised their residential price outlook to a gain of 5% for this year, versus a 10% decline previously.
“Banks and property developer share prices trade at deep discount to book values and in most cases close to their trough valuations,” the Goldman analysts wrote in a note.
“If mortgage loan growth and property market transactions move higher, this could benefit share prices.”
The mortgage easing comes after Hong Kong lowered the stamp duty for first-time buyers of cheaper homes in February.
Despite this, housing affordability has declined after banks raised their prime rate in May, while the one-month Hong Kong interbank rate has spiked.
“The prevailing high rates will act as a big deterrent for most prospective buyers despite the lower sticker prices and lower out-of-pocket expenses,” said Heron Lim, an economist at Moody’s Analytics.
Lim said the latest measures will do little to boost the property market until rates start to come down, probably in mid-2024. “Prices should start making their way up more quickly then,” he said.
(Bloomberg)