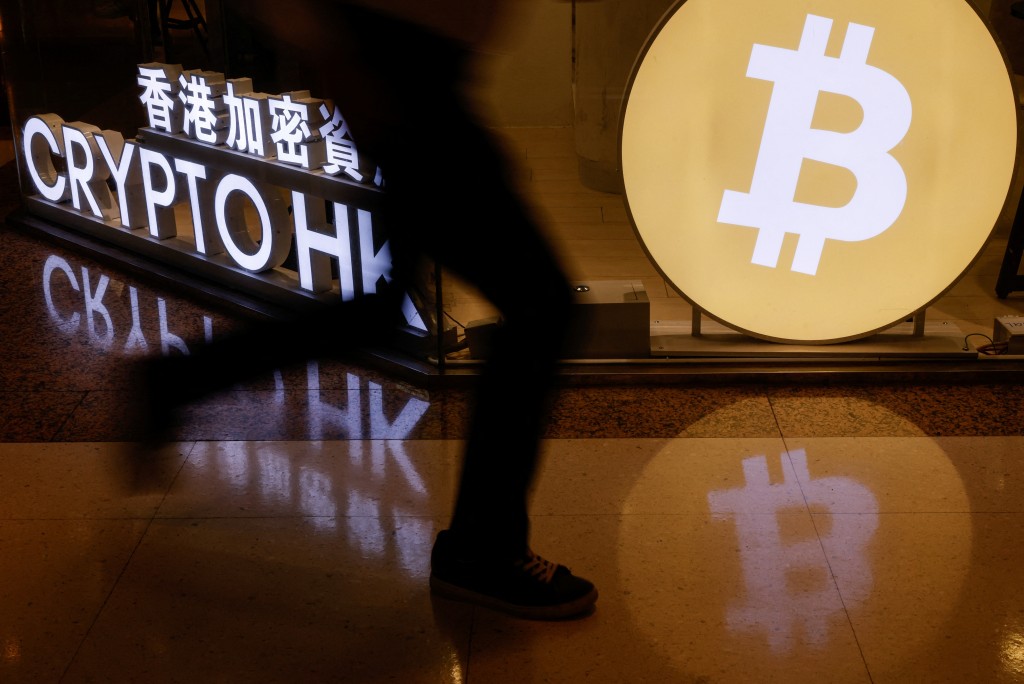
Crypto-asset transactions in Hong Kong will be subject to automatic tax information exchange, as the Legislative Council passed a new reporting framework on Wednesday to combat cross-border tax evasion.
Under the Inland Revenue (Amendment) Bill 2026, relevant crypto-asset service providers must begin collecting user transaction data next year. The Inland Revenue Department will then exchange this data with partner jurisdictions starting in 2028.
The legislation also adopts the latest international standards for digital financial products, with automatic exchanges of general financial account information set to begin in 2029.
“Implementing the latest international standards for automatic exchange of information in tax matters is crucial to maintaining Hong Kong's reputation as an international financial and commercial centre,” said Secretary for Financial Services and the Treasury Christopher Hui Ching-yu.
Hui noted that aligning with global standards would boost industry and investor confidence in operating and making long-term investments in Hong Kong.
The IRD will issue industry guidance and establish a dedicated team to provide technical support and address enquiries from financial institutions.
Since 2018, Hong Kong has conducted automatic financial account information exchanges annually with partner jurisdictions to help tax authorities detect evasion.