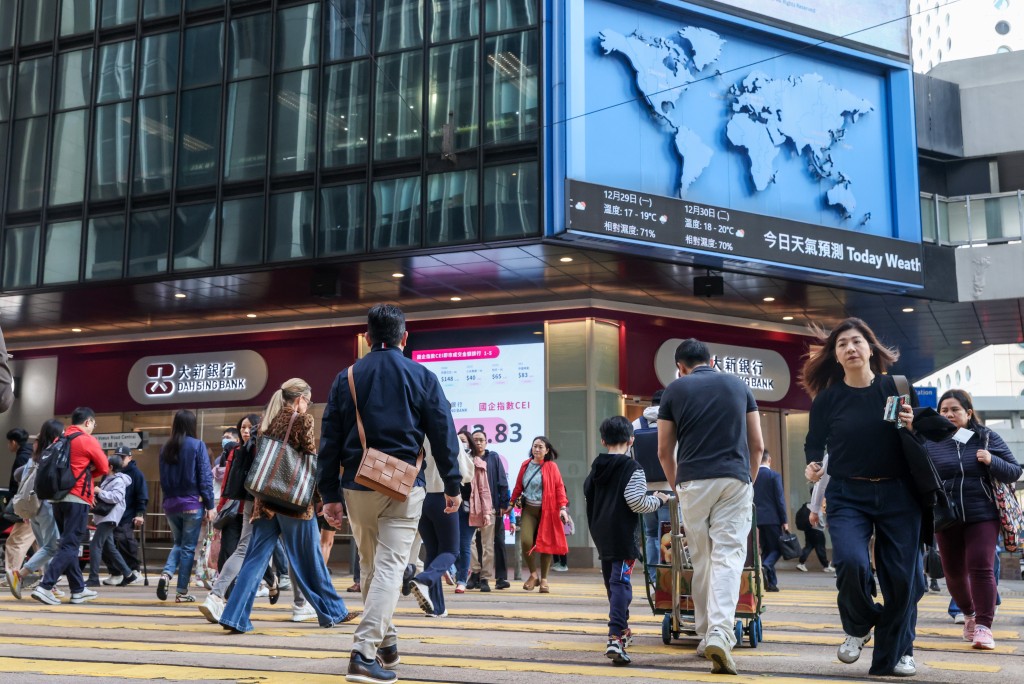
Hong Kong remained the world's second most financially inclusive market in 2026, though declining employer support and falling consumer confidence point to emerging gaps, according to an annual study by Principal Financial and the Centre for Economics and Business Research.
The study evaluated financial inclusion across 42 global markets based on government, financial system, and employer support, drawing on public data alongside a survey of 21,500 household financial decision-makers conducted between April and June.
The city scored 71.4 out of 100 in the 2026 Global Financial Inclusion Index, trailing only Singapore and coming in well above the global average of 52.0. The report ranked Hong Kong second worldwide for government support and sixth for financial system infrastructure, driven by top-tier scores in credit access and online connectivity.
Hong Kong's resilience stems from "the balance between a well-established regulatory and retirement framework and a sophisticated financial system," providing mature infrastructure for financial access, said Thomas Cheong Wee-yee, executive vice-president of Principal Financial and president of Asia Pacific and Middle East.
Employer support lags as public sentiment drops
However, Hong Kong's employer support tumbled eight places to 26th globally with a score of 51.9, the data showed. The decline was dragged down by lower marks for employee pension contributions and workplace pay initiatives.
The proportion of Hong Kong households feeling financially included tumbled 23 percentage points to 64.6 percent over the past four years, down from 88 percent in 2022, according to the survey.
Only 50.1 percent of local respondents viewed employer-provided financial assistance favorably, placing Hong Kong 40th out of the 42 markets polled, the report noted.
Fintech pipeline bolsters long-term outlook
On future competitiveness, the study designated Hong Kong as one of five "Next Gen Leaders" globally, alongside Saudi Arabia, the UK, India, and Colombia, citing its digital infrastructure and potential for fintech-led inclusion.
Pushpin Singh, managing economist at Cebr, said there is a clear link between digital finance and faster gains in financial inclusion, noting that "markets investing in fintech, embedding it in national economic strategy, and developing practical AI applications are therefore likely to build not only more inclusive economies, but stronger ones with greater growth potential".