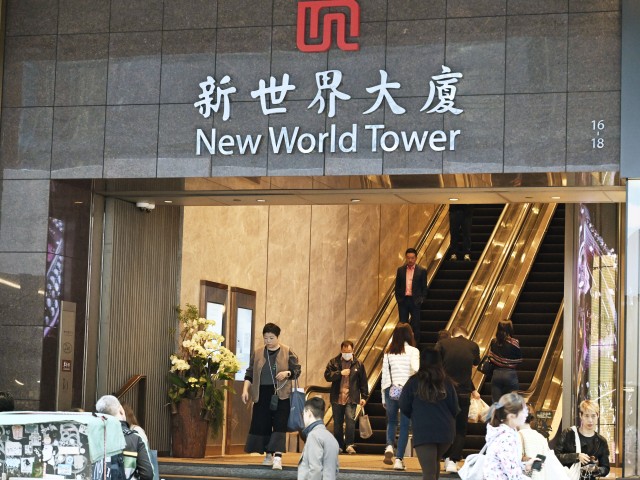
Retail investors of New World Development (0017) face a steep financial hurdle to retain their stakes, as major investment banks slashed the developer's target prices following its highly dilutive HK$24.9 billion rights issue.
For every board lot of 1,000 shares, minority shareholders must shell out HK$9,900 to subscribe to 11,000 rights shares at HK$0.90 each. Those who opt out face a theoretical dilution effect of 75.3 percent.
The massive cash call will swell the developer's issued share capital from about 2.51 billion to 30.2 billion shares, with the newly issued stock accounting for 91.7 percent of the enlarged base.
Mike Leung Kit-man, investment manager at Wocom Securities, advised retail investors unwilling to inject more cash to exit early, warning that NWD might need another cash call in three years if the commercial property market remains weak.
Target prices slashed
The 11-for-1 rights issue has shocked the market with its sheer scale and deep 81.5 percent discount, prompting sweeping downgrades from major banks.
Credit Lyonnais Securities Asia slashed its target price for NWD by more than half to HK$4.46 from HK$10, maintaining a "hold" rating. The brokerage noted the 12-fold increase in shares will lead to a sharp dilution of the book value per share from HK$59.50 down to HK$5.76.
JPMorgan also maintained a "neutral" rating but cut its target price by 58.8 percent to HK$2.80. The bank expects the share price to fluctuate between HK$2 and HK$3 in the near term, noting the capital restructuring will not be a fundamental game-changer for the developer.
Citi kept its target price at HK $6.90 but projected the rights issue will dilute NWD's net asset value per share by 87.8 percent to HK$2.53. The bank estimates earnings per share for the 2027 and 2028 fiscal years will plunge by 81 percent and 92 percent, respectively.
Meanwhile, UBS and Bank of America maintained "sell" and "underperform" ratings on the stock. UBS noted the discount scale shocked the market, though the cash call was not entirely unexpected. Bank of America pointed out the developer's net debt-to-equity ratio remains high at around 75 percent even after treating perpetual bonds as debt, dimming hopes for a near-term dividend resumption.
Airport Authority options
Hong Kong Airport Authority holds options granted by NWD's controlling shareholder Chow Tai Fook Enterprises on September 30 to purchase up to 750 million NWD shares for HK$2.25 billion, or HK$3 per share, within three years.
While the options originally represented a near 30 percent stake, the mega rights issue threatens to dilute that potential holding to just 2.48 percent.
Leung noted that if the stock price drops to around HK$1 after going ex-rights, the authority will have no financial incentive to exercise the HK$3 options. It remains unclear whether the original agreement includes anti-dilution provisions to adjust the strike price.
The options were granted concurrently with an agreement to prematurely terminate the 11 Skies commercial project at the airport.
According to past reports and 2026 estimates by UBS, NWD's guaranteed rent for the project amounted to HK$1.8 billion annually starting in the tenth year, requiring the developer to net at least HK$150 million a month just to break even.