China’s financial policymakers are in Hong Kong this week meeting bankers to seek ways to bolster the city’s status as a hub for investments, deals and talent.
The Ministry of Finance is convening a meeting this Wednesday with bankers as authorities step up efforts to bolster confidence, people familiar with the matter said, asking not to be identified discussing private information. HSBC Holdings Plc, Standard Chartered Plc, Bank of China (HK) are among those invited, the people said.
The discussions will center on how to enhance Hong Kong’s position as an international finance center, its risks and challenges, and how strengthening ties with mainland China can help consolidate its status as a hub, the people said. The ministry didn’t respond to a fax seeking a comment.
Hong Kong is facing grave challenges to maintain its place as an international hub. The city has seen tens of thousand emigrate after years of strict Covid curbs and as China tightened its political grip. Dealmaking has all but dried up as China’s economy struggles to rebound to past levels, with major banks cutting staffing and shifting out of the city and scores of smaller brokers shutting down.
Places such as Singapore have been the beneficiaries with heavy inflows of money, and India’s stock market is fast gaining on the city’s market in terms of size.
China’s top leaders in early November committed to fully back Hong Kong in maintaining its unique status and strengths. Central bank governor Pan Gongsheng has pledged to intensify collaboration with Hong Kong, emphasizing the city’s pivotal role as a link to international markets. He also met with international banks including Morgan Stanley and Goldman Sachs Group Inc.
City leaders have been adamant that Hong Kong is open for business and not losing its luster. They have sought to stem the brain drain by issuing new visas for top talents, sought to lure more family offices and have held high level summits with top bankers.
But leaders have also maintained a heavy focus on national security, even years after protests were quashed, hundreds of people were arrested and newspapers were shuttered.
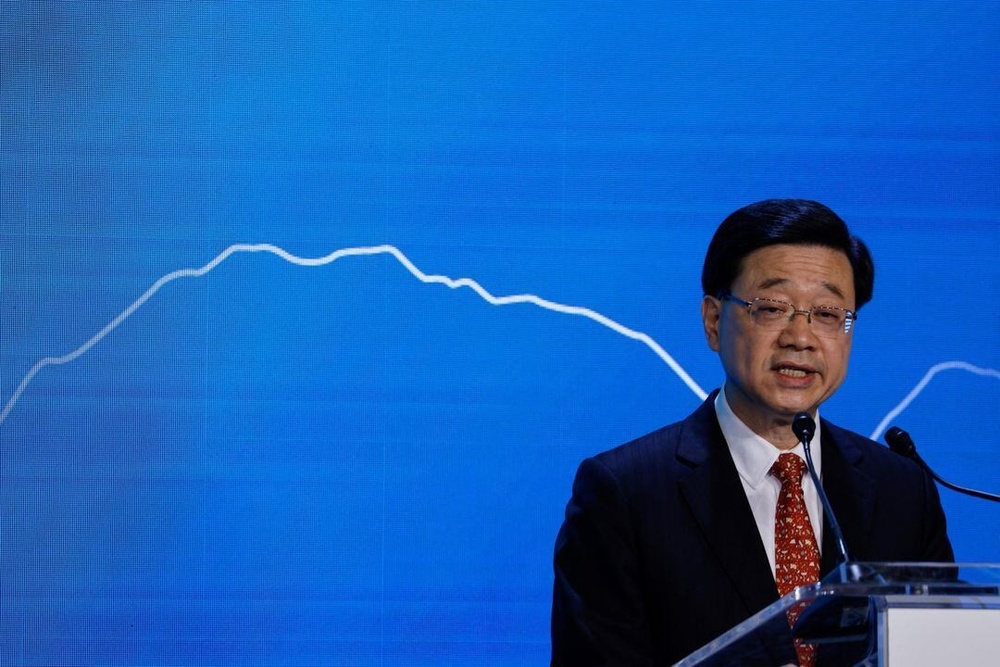
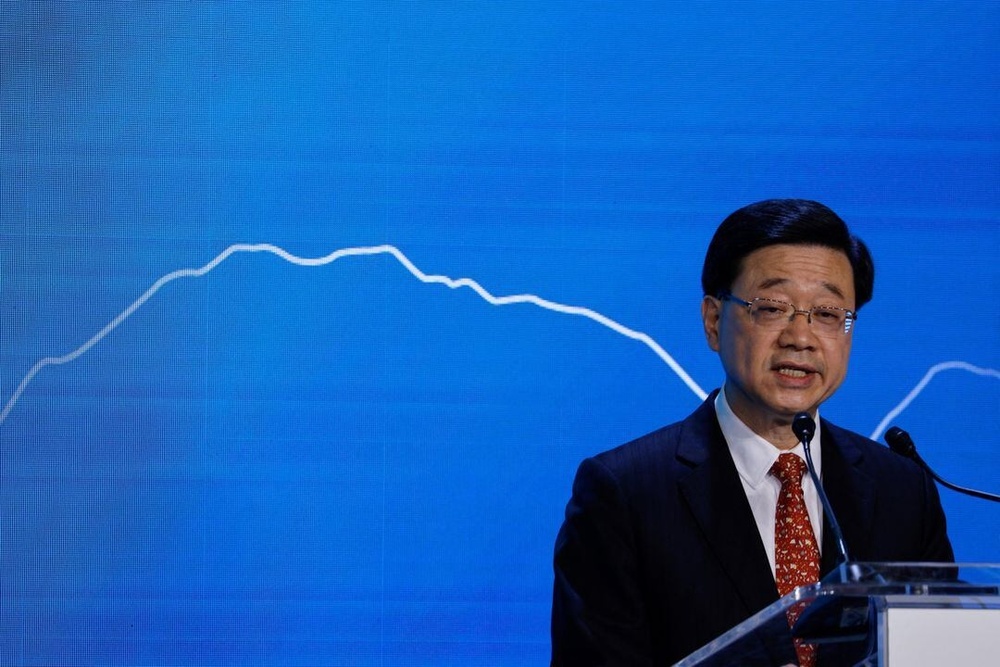
The city’s leader, former policeman John Lee, last week defended his focus on national security, saying most of his policies are on other matters, according to city broadcaster RTHK. At the same time, he also warned that even criticizing government policies on housing and the economy could be a form of “soft resistance.”
Thirty local brokerages have closed down this year, following a record 49 shut up shop in 2022, according to Hong Kong stock exchange data. A drought in deals is adding to the perception of a troubled market. This year is poised to be the worst for Hong Kong IPOs since 2001, marked by a total of $5.1 billion in debuts.
Banks are downsizing, with lenders including Goldman and Morgan Stanley conducting multiple rounds of layoffs in Hong Kong over the past year.
Hong Kong has lowered its economic growth forecast for this year to 3.2% from range of 4%-5%, according to its Census and Statistics Department, signaling tough times are still ahead for the financial hub amid a muted post-pandemic recovery.
HSBC and Standard Chartered declined to comment.
Bloomberg
Hong Kong Chief Executive John Lee speaks during the Global Financial Leaders Investment Summit in Hong Kong, China November 2, 2022. REUTERS/Tyrone Siu