

Read More

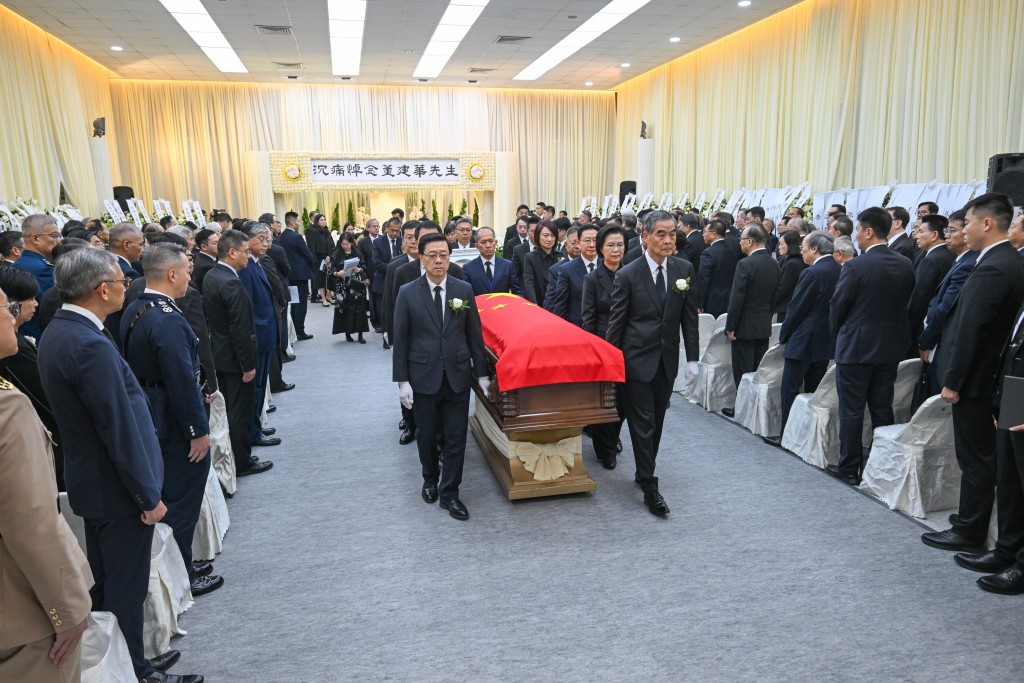
John Lee and CY Leung lead pallbearers for Tung Chee-hwa
20-09-2026 15:54 HKT
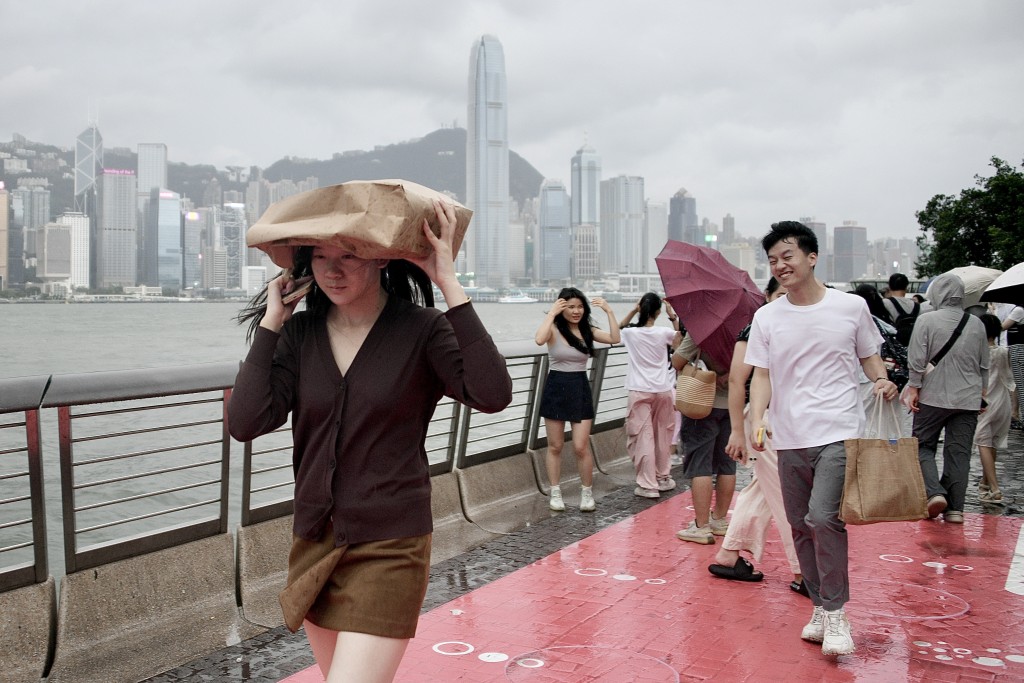
HKO forecasts showers Tuesday, tracks possible cyclone east of Philippines
21-09-2026 17:31 HKT
1. Congratulations to our House Award and Manager of the Year Award winners Chris, Craig, Scott, and Sean! Barings’ outstanding performances won numerous awards, including the High-Yield Fixed Income category last year. Could you share the underlying philosophy with us?
Our philosophy is predicated on the belief that significant inefficiencies exist in the high yield (HY) markets—and our time-tested investment process seeks to exploit them. We believe attractive long-term, risk-adjusted returns can be best achieved through fundamental, bottom-up credit research, combined with dynamic asset allocation across asset classes and geographies.
We apply this approach over a full market cycle by leveraging our extensive investment experience and long-term track records. Our team fully vets each company we follow—including smaller issuers that may fall below the radar screens of peers—which gives us the capacity to generate new, genuinely differentiated, underfollowed ideas.
2. What are some opportunities behind the high yield markets as we advance from this uncertain market condition?
HY bonds have delivered historically attractive returns and also offer diversification benefits due to their low correlation with other asset classes. Compared to loans and IG bonds, HY bonds have, over time, provided the opportunity to pick up additional yield relative to the perceived incremental credit or default risk. Compared to equity-like asset classes, HY bonds have offered comparable returns with less volatility.
Looking at markets today, with prices decoupling from fundamentals and relative value opportunities emerging, we think there are benefits to a flexible approach that allows managers to shift allocations across bonds, loans, and geographies as prices decouple from fundamentals and relative value emerge.
3. What are the inherent risks of HY? Barings also has the industry’s largest global high yield research platform. Do these platforms help your team in risk management?
Default risk is one of the primary risks in HY—but market risk, liquidity risk, interest rate risk, and sector risk also need to be considered. In our view, these risks can be managed through a well-established investment process and team-based culture.
A distinct advantage to our platform is our dedicated, global HY research team of over 40 analysts, which plays a critical role in identifying risks and opportunities. To help mitigate default risk, we rigorously underwrite all initial investments—and monitor companies in real-time to identify any deterioration in fundamentals. We aim to select credits that can withstand headwinds, while our active approach allows us to move away from credits that exhibit fundamental weakness.
Over time, our consistent process has allowed us to deliver consistent and sustainable performance against the benchmark and our peers.
4. Comparing COVID-19 to the global financial crisis (GFC), what is your observation on high yields, and how do you take advantage of the sector at this period of extreme volatility? What suggestions do you have for investors’ asset allocation with different risk profiles?
There have been several risk-on/risk-off periods over the last decade, with dips in the market often being followed by periods of recovery and gains. During the 2008 financial crisis, HY’s spreads saw extreme widening and significant drawdowns—but within 12 months, markets had mostly recovered. Similar scenarios took place during the European sovereign debt crisis in 2011, the energy and commodity shock in 2015, and the fourth quarter of 2018. While every market crisis is different, we have been in similar situations before. We know that times of crisis can ultimately yield opportunity if navigated carefully—which supports the argument for a ‘core’ allocation to HY.
For investors seeking a less aggressive approach, senior secured bonds could be a consideration—as they offer a greater claim to principal protection than unsecured bonds in the event of broader market weakness, while still generating a relatively attractive return.
5. Which sectors, industries, or regions does your team think will favor high yields globally?
Ample liquidity from policymakers has opened the markets to most issuers—even in industries like travel & leisure, entertainment, and retail, companies have been able to access additional capital and look well-positioned to experience a strong recovery when the pandemic recedes. However, uncertainty remains around economic growth and corporate earnings, and investors are understandably asking for better economics and controls.
Thus, we see benefits to moving higher up in the capital structure and considering secured assets. Senior secured bonds are generally twice covered by the value of the business that is pledged to them, which means that if an issuing company defaults, senior secured lenders are in a favorable position relative to unsecured creditors to drive a debt restructuring. All of which has led to strong recoveries over time.
A global approach can also provide benefits. As the U.S. and Europe open their economies at different paces, relative value will likely continue to shift between the two regions. We also think it makes sense for investors to give their fixed-income allocations as much flexibility as possible to capitalize on opportunities as they emerge—efficiently.
6. Can you talk about your ESG and Stewardship policies or other frameworks at Barings has used in the sustainability journey? What is your interpretation of impact?
In 2014, Barings became a signatory to the United Nations’ (UN) Principles of Responsible Investment (PRI) initiative. We have joined several PRI-led initiatives since, including the Global Investor Letter on Climate Change and the ESG in Credit Rating initiative. We are also members of Climate Action 100+. In 2018, the firm became a signatory to the UN’s Global Compact. We also partnered with Pensions for Purpose in the UK and are public supporters of the Task Force on Climate-Related Financial Disclosures.
As fundamental, bottom-up investors, we incorporate ESG through an integrated approach. We separate ESG factors from other risk metrics such as market growth dynamics and cash flow, which allows our team to monitor ESG ratings for individual investments and enables us to make active management decisions based on ESG factors.
From an impact perspective, we are positioned to engage directly with companies on ESG, with a focus on changing behavior and improving disclosure. Through engagement, we aim to enhance the performance of our investments for the benefit of our clients.