Shares in Hong Kong and mainland China soared Tuesday as Beijing ramped up efforts to bolster the country's battered markets.
The two bourses are among the world's worst-performing in 2024, as traders fret over ongoing weakness in the world's second-largest economy, particularly the colossal property sector, as well as government crackdowns on various industries including tech.
China's leadership has become increasingly worried about the sell-off, which has wiped trillions off valuations, and has unveiled a string of measures to try to staunch the rout.
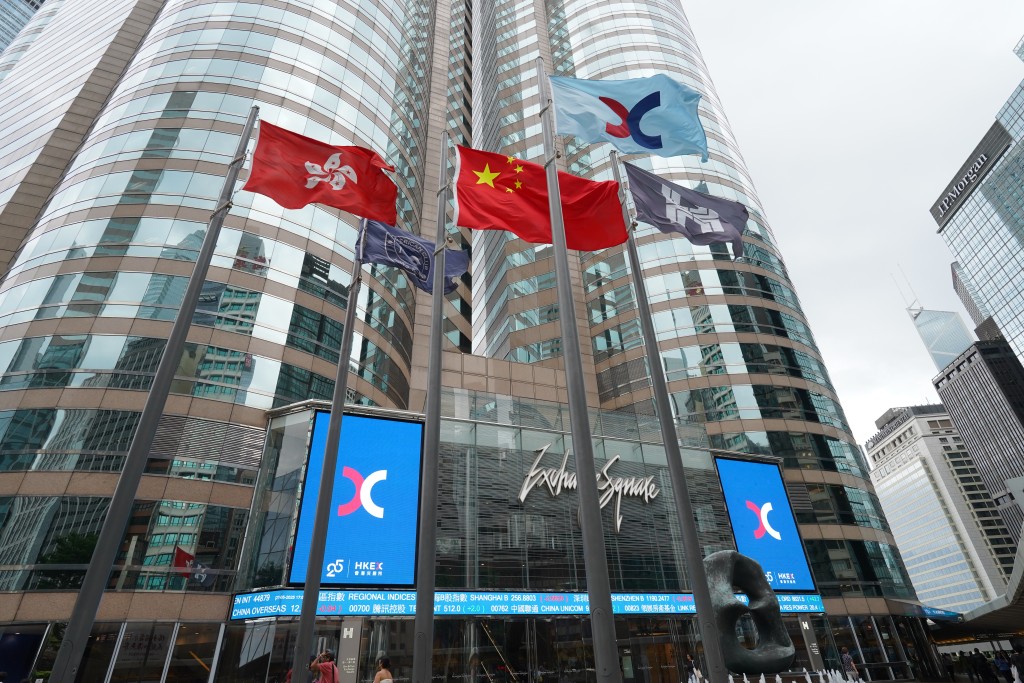
The Hang Seng Index in Hong Kong ended up 4.04 percent, or 626.86 points, to 16,136.87.
The Shanghai Composite Index climbed 3.23 percent, or 87.30 points, to 2,789.49, and the Shenzhen Composite Index on China's second exchange rocketed 5.14 percent, or 73.68 points to 1,506.79.
The advance in Hong Kong was largely helped by a surge in market heavyweight tech firms including Alibaba, JD.com and XD Inc.
On Tuesday, Central Huijin Investment, the unit that holds Chinese government stakes in big financial institutions, said it would increase its exchange-traded fund holdings.
That was followed by the China Securities Regulatory Commission saying it would urge more action from long-term funds and call on listed firms to ramp up repurchases, while Bloomberg reported President Xi Jinping would meet officials to discuss the market's dire performance.
The developments came after officials on Sunday pledged to provide support to avoid wild fluctuations.
(AFP)